Protect what matters · Build what lasts · Leave a legacy
LIFE INSURANCE • INDEXED UNIVERSAL LIFE • RETIREMENT PLANNING • MORTGAGE PROTECTION • FINAL EXPENSE COVERAGE • LEGACY & PROBATE PROTECTION • INCOME PROTECTION • TAX-ADVANTAGED GROWTH • ANNUITIES • GENERATIONAL WEALTH • A+ RATED CARRIERS • LIFE INSURANCE • INDEXED UNIVERSAL LIFE • RETIREMENT PLANNING • MORTGAGE PROTECTION • FINAL EXPENSE COVERAGE • LEGACY & PROBATE PROTECTION • INCOME PROTECTION • TAX-ADVANTAGED GROWTH • ANNUITIES • GENERATIONAL WEALTH • A+ RATED CARRIERS LIFE INSURANCE • INDEXED UNIVERSAL LIFE • RETIREMENT PLANNING • MORTGAGE PROTECTION • FINAL EXPENSE COVERAGE • LEGACY & PROBATE PROTECTION • INCOME PROTECTION • TAX-ADVANTAGED GROWTH • ANNUITIES • GENERATIONAL WEALTH • A+ RATED CARRIERS • LIFE INSURANCE • INDEXED UNIVERSAL LIFE • RETIREMENT PLANNING • MORTGAGE PROTECTION • FINAL EXPENSE COVERAGE • LEGACY & PROBATE PROTECTION • INCOME PROTECTION • TAX-ADVANTAGED GROWTH • ANNUITIES • GENERATIONAL WEALTH • A+ RATED CARRIERS

FINANCIAL STRATEGIST

Build wealth
that's built to last.

I'm Myelani Mpofu - a Licensed Financial Professional, and Educator. I teach families, entrepreneurs, and business owners how money actually works: how to keep more of what they earn, protect what matters most, and build wealth that lasts. Education first with honest conversations, no pressure, ever.

  • Life insurance, living benefits & mortgage protection
  • Tax-advantaged wealth that grows without market risk
  • A+ rated carriers, matched to your family and budget
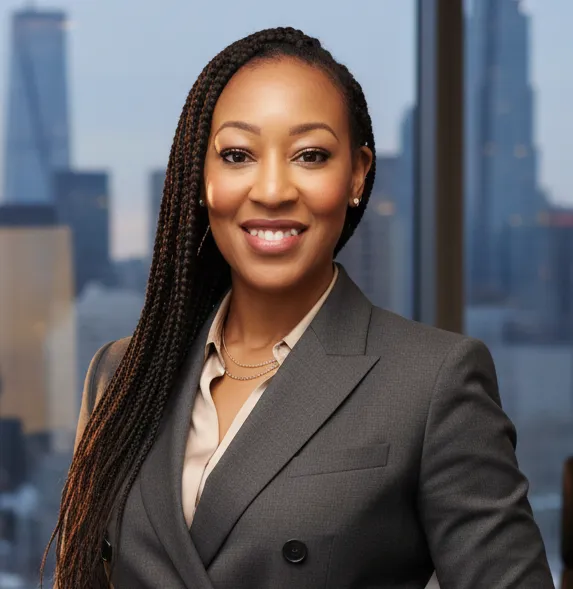
Myelani Mpofu
— WHY THIS MATTERS

Most families are one setback away from starting over.

Not because they don’t work hard — but because no one ever sat down at their kitchen table and built them a real plan. That is exactly what I do.

63%

live paycheck to paycheck — even six-figure earners

Income is coming in, but nothing is truly being built — and millions of those households earn over $100,000. Breaking the cycle starts with a written plan: know where the money goes, automate savings first, and protect the income everything depends on.
DETAILS ▾
53%

couldn’t cover a $1,000 emergency from savings

One car repair, medical bill, or missed paycheck can push a household straight into debt. An emergency fund is the foundation under every other strategy — we build it into the plan before anything else.
DETAILS ▾
31%

could handle less than $500 in an emergency

That includes 18% who say they could cover less than $100. Small buffers fail at the worst moments — a right-sized emergency fund plus income protection keeps one bad week from becoming a bad decade.
DETAILS ▾
64%

say credit card debt delays life’s big decisions

Saving, investing, buying a vehicle — debt keeps pushing them back a year at a time. We sequence it: attack high-interest debt while keeping protection and retirement contributions alive, so progress never fully stops.
DETAILS ▾
40%

carry medical or dental debt today

For millions of families, a health issue quickly becomes a financial crisis. Health events are the number-one budget breaker — the right coverage mix keeps a diagnosis from draining what you’ve built.
DETAILS ▾
73%

fail a basic financial knowledge quiz

Most Americans can’t correctly answer five of seven basic money questions — because most of us were never taught. Education is the first thing I deliver: plain-language answers before any product is ever discussed. The question library below is exactly that.
DETAILS ▾
50%

have no life insurance protection at all

Millions of families have nothing in place if an income earner dies unexpectedly. Term coverage often costs less than people guess — we right-size a number to your income, mortgage, and kids, not a generic chart.
DETAILS ▾
40%

are uninsured or underinsured — ~100M people

Coverage through work is rarely enough and rarely portable — many policies cover just one or two times salary. A quick audit shows the gap between what you have and what your family would actually need.
DETAILS ▾
40%

have no retirement investments at all

For millions of people, retirement is not a plan — it is a hope. The calculator below turns “someday” into a number — your Financial Independence Number — and a monthly savings plan to reach it.
DETAILS ▾
67%

say money is a significant source of stress

Financial pressure doesn’t stay on a spreadsheet — it shows up in health, marriages, energy, and sleep. Clarity is the antidote: families tell me the biggest change after planning isn’t the money, it’s sleeping better.
DETAILS ▾
— The Mission

Four conversations that change a family’s trajectory.

Every household Seline works with starts here. These aren’t products — they’re the four protected areas every family needs handled before anything else gets built.

Conversation 01

Income Protection

A breadwinner’s most valuable asset is their next 30 years of income.

Life and disability protection means that asset is never gambled — even on the worst day. We size the coverage to your income, your mortgage, and the years your family depends on you, so one bad day never becomes a financial catastrophe.
Learn more ▾
Conversation 02

Debt Elimination

A debt-free household ten or twenty years sooner than the bank planned.

Real strategies, real math: structured payoff sequences that compound, freeing up the cash flow that funds everything else in your plan. We sequence it so protection and retirement contributions never stop while the debt comes down.
Learn more ▾
Conversation 03

Retirement You Won’t Outlive

Tax-advantaged growth and guaranteed income that holds up against real-life math.

Guaranteed income vehicles, protection from market downturns at the worst possible moment, and a withdrawal plan stress-tested against longevity. The calculator below turns “someday” into a number — then we build the plan to reach it.
Learn more ▾
Conversation 04

Generational Wealth Transfer

What you build should outlive you — and reach your family intact.

Estate strategies, beneficiary planning, and tax-efficient transfer. Life insurance proceeds generally pass directly to named beneficiaries — outside probate — making it one of the cleanest ways to move wealth to the next generation.
Learn more ▾
THE TOOLKIT

The right tool for each family’s plan.

No single product fits every household. Myelani works through a full suite of A+ rated carriers to match the right tool to your situation, timeline, and budget. Tap any solution to see how it works.

No. 01

Indexed Universal Life (IUL)

Permanent coverage with cash value linked to a market index — growth in good years, protection in bad ones.

Learn more ▾
Tax-advantaged growth, tax-free policy loans, and a death benefit that protects your family — capturing index-linked gains while a floor protects against market losses. Best for: families wanting protection and a tax-advantaged growth vehicle they can access during life.
No. 02

Term Life Insurance

Maximum death benefit for the lowest premium, locked in for 10, 20, or 30 years.

Learn more ▾
The simplest, most cost-effective way to protect your family during the years it matters most — paying off the mortgage, raising the kids, building wealth. Best for: young families and breadwinners who need significant protection during peak earning years.
No. 03

Whole Life Insurance

Guaranteed cash value growth and a guaranteed death benefit that never expires.

Learn more ▾
Premiums stay level for life, and the policy builds an asset on your balance sheet you can borrow against tax-free for opportunities or emergencies. Best for: families who want lifetime certainty, predictable growth, and an asset that doubles as protection.
No. 04

Annuities

Contractual income vehicles that turn retirement savings into a paycheck you cannot outlive.

Learn more ▾
Fixed and indexed options offer principal protection from market downturns with growth potential — and guaranteed lifetime income when you’re ready to take it. Best for: pre-retirees and retirees worried about running out of money or losing principal in a crash.
No. 05

Mortgage Protection

Term coverage structured to match your mortgage balance and timeline.

Learn more ▾
If something happens to a breadwinner, the policy pays off the mortgage — so your family keeps their home no matter what. Best for: homeowners with a family who depends on that home staying in their name.
No. 06

Final Expense Insurance

Smaller whole life policies covering funeral costs and end-of-life bills.

Learn more ▾
Affordable premiums, simplified underwriting, lifetime coverage — so your kids and grandkids don’t inherit a bill on top of their grief. Funerals commonly run $9,000–$15,000. Best for: seniors and anyone wanting to spare loved ones from final costs.
Know the Number. Build the Plan.

What’s your Financial Independence number?

Find out how much you may need invested to create the retirement income you want — and how much you may need to save each month to get there.

Example: to create $100,000/year using a 4% withdrawal strategy, you may need approximately $2.5 million invested.

Most people want to retire someday. Very few know their number.

Your Financial Independence Number is the amount of invested money you would likely need to create the retirement income you want — without depending only on a paycheck, Social Security, or guesswork.

A common rule of thumb is the 4% withdrawal strategy: if your investments are large enough, you may be able to withdraw about 4% of the balance each year to help fund your retirement lifestyle.

The Simple Formula
Desired annual income × 25 = your Financial Independence Number

The goal is not to scare you. The goal is to give you clarity.

Without a clear target, saving for retirement feels vague and overwhelming. Once you know your number, you can reverse-engineer the plan — and estimate:

  • How much you may need invested by retirement
  • How much you should be saving each month now
  • How long it may take to reach your goal
  • Whether your current strategy is on track
  • What changes may help close the gap
Calculate Your Financial Independence Number
Interactive Planner
$100,000
$50,000
$1,000
40
65
7%
$2,000
$0
Your Financial Independence Number
$1.90M
investments must produce $76,000/yr after your $24,000/yr in expected benefits
Additional Monthly Savings Needed
$992
additional per month, on top of your current $1,000/mo
Your current trajectory ($50,000 + $1,000/mo) by age 65 58%

Your Starting Action Plan

  1. Your expected benefits do real work: $24,000/yr in Social Security and other income covers 24% of your goal — your investments only need to produce $76,000/yr.
  2. Raise your monthly savings from $1,000 to about $1,992/month — an increase of $992. Automate it on payday so it happens before spending can.
  3. You have 25 years (300 monthly contributions). Every year you wait raises the monthly number — starting now is the biggest lever you have.
  4. Your current trajectory is already working: $50,000 invested plus $1,000/mo could grow to about $1.10M by age 65 — covering 58% of your target.
  5. Pressure-test the plan with a professional — the right strategy can address taxes, market risk, and protecting your income while you build.
These figures are hypothetical estimates for educational purposes only and are not a guarantee, projection of actual results, or financial, tax, or investment advice. The 4% withdrawal concept is a rule of thumb, not a promise; actual sustainable withdrawal rates vary with markets, taxes, fees, inflation, and personal circumstances. Calculations assume monthly compounding at the selected rate of return, which is not guaranteed. Social Security and pension amounts are user-provided estimates; actual benefits depend on your earnings record, claiming age, and program rules, and are not guaranteed by this tool. Please consult qualified professionals about your specific situation.

Want help building the plan?

Knowing your number is powerful — but the real work is building a strategy to reach it. A financial strategy can help you organize your savings, protect your income, reduce unnecessary financial risk, and create a clearer path toward long-term independence.

SCHEDULE A CONVERSATION
— THE PROCESS

How working with Myelani actually looks.

A clear, no-pressure process designed around your timeline. No surprises and no high-pressure tactics — just a structured conversation followed by a custom plan.

1

A 15-Minute Conversation

Book a no-cost intro call. Myelani learns about your household, your goals, and what’s keeping you up at night. If it’s not the right fit, she’ll tell you on this call.

2

A Financial Snapshot

Together you map where you are today — income, debts, protection in place, retirement assets, and gaps. No judgment, no pressure to act. Just clarity.

3

A Written Custom Strategy

A plan tailored to your numbers, your budget, and your timeline. You see exactly what you’d be doing, why, and what it costs — before you commit to anything.

4

Implementation, Your Pace

When you’re ready, Myelani puts the strategy in motion — paperwork, carrier selection, beneficiary setup, the works. You control the pace.

5

Ongoing Reviews

Life changes — marriages, kids, raises, moves, market shifts. Regular reviews make sure the plan still fits the life you’re actually living.

Families don’t need another sales pitch. They need a clear plan, an honest conversation, and someone who will still be there a year from now to answer the phone.

— Myelani Mpofu